The short answer
Funding and growth planning gets your business ready for a loan, line of credit, SBA application or investor conversation. At AZ Easy CFO, Chris Badulescu, CPA, cleans up the story your numbers tell, builds projections that hold up to questions and assembles the package lenders typically ask for.
What do lenders want to see before approving a business loan?
Lenders want consistent, reconciled financial statements, a clear picture of your existing debt and a believable plan for repaying the new loan. They also look at how your books line up with your tax returns. Gaps or surprises slow the process or end it.
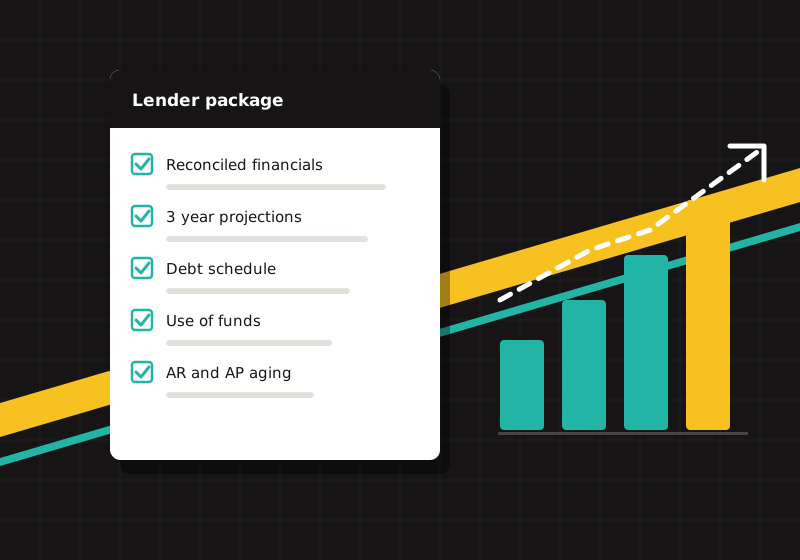
- Two to three years of financial statements, plus year to date
- Business tax returns that match the books
- A debt schedule showing every current loan and lease
- Accounts receivable and payable aging reports
- Financial projections showing how payments fit
- A short explanation of how the funds will be used
The U.S. Small Business Administration outlines common requirements for SBA backed loans, and each lender adds its own.
How do you build financial projections a lender will trust?
We start from your actual history, not a wish. Projections tie back to real revenue trends, margins and costs, with each assumption written down. Lenders trust projections they can trace, so we show the math and keep the assumptions conservative.
- Baseline. Clean, reconciled history from your books.
- Assumptions. Growth, pricing, hiring and cost changes, each documented.
- Three statements. Projected income statement, balance sheet and cash flow that agree with each other.
- Debt service. How the new payment fits, including coverage ratios lenders commonly check.
- Sensitivity. What happens if growth comes in slower than planned.
Projections build on the same model as your cash flow forecast, so the story stays consistent.
Can you help with an SBA loan application?
Yes, on the financial side. We prepare the financial statements, projections, debt schedule and supporting reports that SBA lenders typically request, and help you answer their follow up questions. The lender makes the credit decision, and we do not act as a broker.
SBA applications involve a lot of paperwork, and the financial pieces are where many applications stall. Having a CPA prepare and review them can make the process smoother, but approval always depends on the lender and your overall situation. Nothing about funding is guaranteed.
What is included in growth planning?
Growth planning maps out where the business is going and what it will take financially to get there: revenue targets, hiring, capital needs, pricing and timing. It turns big goals into a plan with numbers attached, so you can see what has to be true for the goal to work.
- Revenue and profit targets by year, broken down by month
- Hiring plan and the revenue needed to support each role
- Capital needs: equipment, locations, working capital
- Pricing and margin strategy
- Business plan financials for partners, investors or lenders
- Exit and succession planning when the time comes
When should I start preparing for funding?
Ideally three to six months before you need the money. That leaves time to clean up the books, resolve any mismatches with tax returns, build projections and fix issues a lender might flag. Starting early also lets you apply from a position of strength rather than urgency.
The best time to borrow is often when you do not urgently need to. If cash is already tight, start with a 13 week cash forecast so you know exactly how much you need and when.
How do we get started?
Free consultation
Tell Chris what you are planning and what funding you are considering.
Readiness review
We review your books, tax returns and debt to spot anything a lender might question.
Clean up and build
We resolve issues, then build projections and the supporting reports.
Assemble the package
You get an organized, consistent lender package and talking points.
Support through questions
We help you answer follow up questions from the lender or investor.
Funding and Growth Planning questions
Do you guarantee loan approval?
No. Lending decisions belong to the lender and depend on many factors. Our job is to make sure your financial information is accurate, organized and clearly presented.
Are you a loan broker?
No. We do not arrange loans or take a commission from lenders. We prepare your financial information so you can work with the lender of your choice.
Can you write my business plan?
We prepare the financial sections of a business plan: projections, assumptions, use of funds and break even analysis. The narrative sections stay in your voice, and we can review them for consistency with the numbers.
How far out should projections go?
Most lenders ask for one to three years. Investors may want longer. We match the projection period to what your lender or investor requests.
What if my tax returns and books do not match?
This is common and fixable. We identify the differences, explain them and work with your tax preparer so the numbers line up before you apply.
Can you help me plan for selling the business?
Yes. Exit planning starts with clean financials and a clear picture of profitability, often a few years before a sale. We coordinate with your attorney, broker and tax advisor.